
For families with assets in several countries, a trust can help manage wealth, plan for future generations and support relatives. However, when a family member becomes a U.S. citizen or tax resident, an existing foreign trust can create unexpected U.S. tax and reporting obligations.
One of the most important questions is whether the arrangement is classified as a foreign grantor trust or a foreign nongrantor trust under U.S. tax law. This distinction affects who is treated as earning the trust’s income, how distributions to U.S. beneficiaries are taxed and which information returns may be required.
The answer depends on the trust’s terms, who contributed the assets, the powers retained by the grantor and the beneficiaries’ circumstances.
International Tax Consultants (ITC) helps individuals and international families understand U.S. tax compliance involving foreign trusts, cross-border wealth and family distributions. Reviewing a trust before a significant distribution or restructuring can help identify potential tax and reporting issues.
1. What Is the Difference Between a Grantor Trust and a Nongrantor Trust?
For U.S. tax purposes, the key question is whether another person is treated as the owner of some or all of the trust’s assets under the grantor-trust rules.
Foreign grantor trust
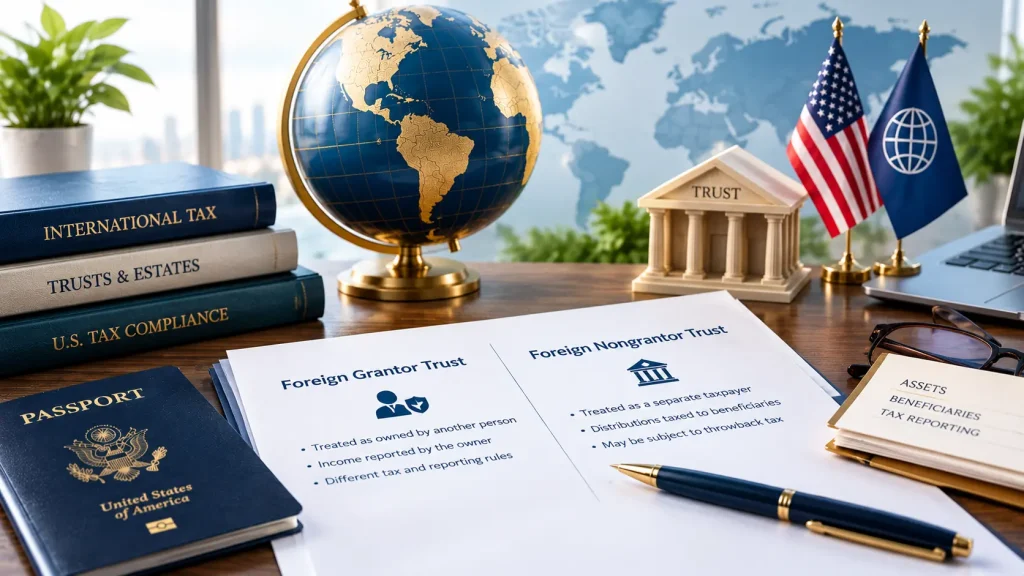
A foreign grantor trust is a foreign trust whose assets, or a portion of them, are treated as owned by another person under U.S. tax law. The income attributable to that portion is generally reported by the person treated as its owner.
The person who established the trust is not automatically its U.S. tax owner. Special rules apply to foreign grantors, and the outcome depends on the trust’s terms, retained powers and applicable statutory provisions.
Foreign nongrantor trust
A foreign nongrantor trust is a trust whose assets are not treated as owned by another person under the grantor-trust rules. It is generally treated as a separate taxpayer, and distributions to U.S. beneficiaries are analysed under the applicable trust distribution rules.
A trust may also be treated as a grantor trust for one portion of its assets and a nongrantor trust for another.
The important point: The trust deed’s terminology or classification under foreign law does not determine its U.S. tax treatment. The arrangement must be assessed under U.S. tax rules.
2. Foreign Grantor Trusts: Are Distributions Tax-Free?
Families sometimes assume that payments from a foreign parent’s trust to a child living in the United States are automatically tax-free gifts. That is not always correct.
U.S. law restricts when a foreign person can be treated as the owner of a trust under the grantor-trust rules. Specific exceptions may apply, including certain arrangements involving a grantor’s power to revoke the trust or restrictions on who can receive distributions during the grantor’s lifetime. The exact requirements are technical and depend on the facts.
How are distributions treated?
If a trust qualifies as a foreign grantor trust and the beneficiary receives the required Foreign Grantor Trust Beneficiary Statement, a distribution is generally treated for U.S. income tax purposes as if it came directly from the owner.
For example, if the payment is properly treated as a gift from the foreign owner, the beneficiary generally does not include the gift in gross income. However, the result depends on the circumstances and supporting documentation.
Income tax treatment and information reporting are separate issues. A distribution that is not taxable income may still be reportable on Form 3520. A foreign trust with a U.S. owner may also have annual reporting obligations, including Form 3520-A.
Before relying on this treatment, families should establish:
- Who contributed the trust assets and who is treated as their owner under U.S. law.
- What powers the grantor retains and who may receive distributions.
- Whether the required beneficiary statement and annual information returns are being prepared.
- Whether other U.S. tax rules apply to the trust’s income or distributions.
Professional review can help identify problems before a distribution is made.
3. Foreign Nongrantor Trusts: How Are Distributions Taxed?
For a foreign nongrantor trust, the U.S. tax treatment of a beneficiary’s distribution depends on factors including the trust’s distributable net income (DNI), accumulated income and the nature of the payment.
Current-year income
A U.S. beneficiary generally includes the applicable portion of distributed DNI in income, subject to the relevant tax rules. DNI helps determine how much of a trust distribution carries taxable income to a beneficiary. It is not necessarily the same as the cash held in the trust’s bank account or its total investment return.
The character of the income can also affect its treatment. Interest, dividends and other income may not all receive identical tax treatment.
Accumulated income and the throwback tax
When a foreign nongrantor trust retains income and distributes it in a later year, the distribution may qualify as an accumulation distribution. Certain accumulation distributions can trigger the foreign trust throwback tax, which involves a special tax calculation and an interest charge.
Not every payment of funds held for several years is automatically subject to the throwback rules. The trust’s accounting, income history, previous distributions and applicable tax provisions must be reviewed.
A beneficiary should not assume that a large payment is tax-free simply because the trustee describes it as principal. Equally, the entire payment should not automatically be treated as ordinary income without analysing the facts.
What about trust principal?
A genuine distribution of trust principal may receive different treatment from a distribution of taxable income. However, calling a payment “principal” does not establish its tax treatment.
Trust records must be examined to determine whether the distribution represents principal, current-year income, accumulated income or a combination. Accurate records are especially important for long-standing trusts and arrangements involving multiple generations.
4. What Happens When the Foreign Grantor Dies?
The death of the person who established a foreign trust can change its U.S. tax treatment, particularly if the trust’s grantor status depends on rights held during that person’s lifetime.
However, it is not correct to assume that every foreign grantor trust automatically becomes a nongrantor trust after the grantor dies. The result depends on the trust deed, applicable tax provisions and the arrangement’s circumstances.
Families should review the trust before the grantor’s death where possible and reassess it promptly after a death or other significant change.
Key questions include:
- How will the trust be classified after the grantor’s death?
- What happens to income accumulated in earlier years?
- How will future distributions to U.S. beneficiaries be treated?
- Are different information returns or other reporting steps required?
- Are the trust’s records sufficient to support the tax treatment of distributions?
Reviewing these issues early can help families avoid making distribution decisions without understanding the potential U.S. tax consequences.
5. Foreign Grantor Trust vs. Nongrantor Trust: Key Differences
| Issue | Foreign grantor trust | Foreign nongrantor trust |
| Who is treated as owner? | Another person is treated as owning some or all of the assets under the grantor-trust rules. | The trust is generally treated as separate from its beneficiaries for the portion not treated as owned by another person. |
| How is income treated? | Relevant income is generally attributed to the person treated as the owner. | Beneficiary tax consequences generally depend on distributions and the applicable trust rules. |
| Are distributions taxable? | Depends on the owner, the nature of the payment and the required documentation. | Generally taxable to the extent of applicable DNI, with special rules for accumulated income and other amounts. |
| Can the throwback tax apply? | Generally not to income already treated as owned and taxed under the grantor-trust rules, although the facts must be reviewed. | May apply to qualifying accumulation distributions. |
| Is Form 3520 required? | May be required for reportable transfers, distributions or other applicable events. | Generally required for reportable distributions and other applicable transactions. |
| Is Form 3520-A required? | Generally relevant when the foreign trust has a U.S. owner under the grantor-trust rules. | Generally not required solely because the trust is a nongrantor trust, unless a portion is treated as owned by a U.S. person. |
These are general distinctions. The correct classification and filing requirements must be confirmed for the specific trust and tax year.
6. Planning Options for Families With U.S. Beneficiaries
There is no single trust structure that suits every international family. Planning depends on the family’s objectives, the assets involved, the trust’s terms and the U.S. tax status of the grantor and beneficiaries.
Review the trust deed and ownership
Start by reviewing the trust deed, amendments, grantor powers, beneficiary provisions and distribution history. A trust described as a grantor trust under foreign law may receive a different classification under U.S. tax rules.
Establish an annual reporting process
A foreign trust with a U.S. owner generally has an annual Form 3520-A filing obligation. The U.S. owner is responsible for ensuring that the filing and required statements are provided. If the foreign trust does not file, the U.S. owner may need to file a substitute Form 3520-A.
U.S. beneficiaries may separately need to file Form 3520 for distributions and other reportable events. These forms serve different purposes, and filing one does not automatically satisfy every reporting obligation.
Review distribution decisions
Some families consider distributing current-year income rather than allowing it to accumulate. Depending on the circumstances, this may affect future accumulation-distribution issues.
However, current distributions do not automatically eliminate throwback-tax exposure relating to income accumulated in earlier years. Changes to distribution policies should be assessed against the trust deed, beneficiaries’ needs and the applicable tax rules.
Assess whether a domestic trust is appropriate
In some circumstances, a family may consider restructuring an arrangement or establishing a domestic trust. For U.S. federal tax purposes, a trust generally must satisfy both the court test and the control test to qualify as domestic.
Moving assets, appointing a U.S. trustee or changing the trust’s name does not, by itself, establish domestic status. Restructuring can also create other tax and legal consequences, including issues involving accumulated income, past reporting obligations and the laws of other jurisdictions.
Obtain professional advice before changing the trust’s structure or distribution arrangements.
Frequently Asked Questions
Can a foreign trust distribute tax-free money to a U.S. citizen?
Sometimes. A distribution from a foreign grantor trust that is properly treated as a gift from its foreign owner generally is not included in the beneficiary’s gross income. The trust’s classification, the nature of the payment and the required documentation must be reviewed. Form 3520 reporting may still apply.
What happens when the foreign grantor dies?
The trust’s tax treatment may change if its grantor status depended on the grantor’s lifetime rights. The result depends on the trust deed and applicable rules, so the family should reassess the arrangement rather than assume it automatically becomes a nongrantor trust.
Does a U.S. beneficiary pay tax on trust principal?
A genuine distribution of principal may be treated differently from a distribution of income. The trust’s accounting and distribution records must support the classification, particularly where income has accumulated over several years.
Does every foreign trust require Form 3520-A?
No. Form 3520-A generally applies to a foreign trust with a U.S. owner under the grantor-trust rules. A foreign nongrantor trust without a U.S. owner generally does not file Form 3520-A solely because it has U.S. beneficiaries. Other reporting obligations may still apply.
What if Form 3520 or Form 3520-A was not filed?
Penalties may apply, depending on the type of reporting failure and the circumstances. Reasonable-cause relief may be available in qualifying cases, but it is not automatic. If a filing was missed or the IRS has issued a notice, seek professional advice about the appropriate response.
Get Professional Guidance on Your Foreign Trust
Understanding whether a foreign trust is a grantor or nongrantor trust is an important first step in determining how income, distributions and reporting obligations are treated under U.S. tax law.
The outcome may also depend on accumulated income, the grantor’s rights, distribution records and changes in family circumstances. An incorrect assumption can lead to unexpected tax liabilities or missed information returns.
International Tax Consultants (ITC) assists individuals and international families with U.S. international tax compliance and foreign trust matters.
If you are a U.S. beneficiary of a foreign trust, are planning a family distribution or need help reviewing previous filings, contact International Tax Consultants to discuss your circumstances and the professional assistance you may need.